<script type="application/ld+json">[{"@context":"https://schema.org","@type":"Article","headline":"Car Finance Complaints While the Redress Scheme Is on Hold: Should You Wait or Complain Now?","description":"The Upper Tribunal will hear the challenge to the FCA's car finance scheme in February 2027. See what the delay means for your complaint.","url":"https://www.pcpmissold.co.uk/news/car-finance-complaint-wait-or-complain-now","datePublished":"2026-10-21","dateModified":"2026-10-21","mainEntityOfPage":{"@type":"WebPage","@id":"https://www.pcpmissold.co.uk/news/car-finance-complaint-wait-or-complain-now"},"publisher":{"@type":"Organization","name":"PCP Missold Ltd","url":"https://www.pcpmissold.co.uk","logo":{"@type":"ImageObject","url":"https://www.pcpmissold.co.uk/images/logo.png"}},"author":{"@type":"Person","name":"Shane Lowe","jobTitle":"Content Lead","worksFor":{"@type":"Organization","name":"PCP Missold Ltd"}}},{"@context":"https://schema.org","@type":"BreadcrumbList","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://www.pcpmissold.co.uk"},{"@type":"ListItem","position":2,"name":"News","item":"https://www.pcpmissold.co.uk/news"},{"@type":"ListItem","position":3,"name":"Car Finance Complaints While the Redress Scheme Is on Hold: Should You Wait or Complain Now?","item":"https://www.pcpmissold.co.uk/news/car-finance-complaint-wait-or-complain-now"}]},{"@context":"https://schema.org","@type":"FAQPage","mainEntity":[{"@type":"Question","name":"Is the FCA's car finance compensation scheme still going ahead?","acceptedAnswer":{"@type":"Answer","text":"The scheme is partially suspended while the Upper Tribunal considers four legal challenges. The FCA says it will defend the scheme and that lenders must keep preparing. The hearing runs from 16 to 26 February 2027, with judgment expected afterwards. Until then, lenders do not need to calculate or pay compensation under it."}},{"@type":"Question","name":"Do I have to wait until February 2027 to complain?","acceptedAnswer":{"@type":"Answer","text":"No. The FCA says you can complain to your lender now, free of charge. Payments under the scheme stay paused until the legal process ends, so waiting and complaining now both depend on the Tribunal's outcome. The right timing is your decision, and the FCA's guidance is the best place to check the latest position."}},{"@type":"Question","name":"Can my lender tell me I am owed nothing while payments are paused?","acceptedAnswer":{"@type":"Answer","text":"Yes. The FCA says lenders must keep complying with the scheme rules still in force, which includes writing to some customers who are not owed compensation. The dates depend on when you complained. Equally, not hearing back does not mean you are owed money, as the FCA points out."}},{"@type":"Question","name":"Do I need a claims company or solicitor to complain?","acceptedAnswer":{"@type":"Answer","text":"No. The FCA says you do not need a claims management company or law firm to complain or to receive compensation under its scheme, and the scheme is free to use. If you choose a representative, check the fees first and avoid signing up with more than one firm."}},{"@type":"Question","name":"What happens if the Tribunal rules against the scheme?","acceptedAnswer":{"@type":"Answer","text":"The FCA has told lenders to plan for that possibility. If the scheme or parts of it are quashed, there may be no scheme and no pause on complaints, and lenders would need to handle complaints through their usual process within the usual statutory timescales. The outcome remains uncertain until the Tribunal rules."}}]}]</script>

News

Car Finance Complaints While the Redress Scheme Is on Hold: Should You Wait or Complain Now?

October 2026
Shane Lowe

On 13 October 2026, the FCA confirmed that the Upper Tribunal will hear the legal challenges to its motor finance compensation scheme between 16 and 26 February 2027, with a judgment expected in the months that follow. For anyone waiting on a car finance complaint, the date raises an obvious question: should you hold off until the outcome is clear, or complain now?

This guide sets out what the FCA has said about the delay, what lenders must still do while payments are paused, and what your options are. It cannot tell you whether you are owed anything or when you might be paid, because nobody can yet. What it can do is help you decide with accurate information.

IN THIS ARTICLE

  • What the February 2027 hearing means for car finance compensation
  • What lenders still have to do while payments are paused
  • Should you wait or complain now?
  • How to complain to your lender, step by step
  • What to watch for while you wait
  • Frequently asked questions

What the February 2027 hearing means for car finance compensation

The scheme was challenged by three lenders, Volkswagen Financial Services, Mercedes-Benz Financial Services and Crédit Agricole Auto Finance, and by the group Consumer Voice, according to the FCA's statement of 13 October 2026. The scheme is currently partially suspended. Until the legal process ends, the FCA says lenders do not need to calculate or pay compensation to people who are owed money under it.

If the Tribunal upholds the scheme and its judgment is not appealed, the FCA expects payments to begin in 2027. A ruling against the scheme, or an appeal, would change that picture. Some lawyers quoted by Insurance Business think payments could slip later still. For background on how the scheme works, see our guide to the motor finance redress scheme.

Key points from the FCA

  • The Upper Tribunal will hear the challenges from 16 to 26 February 2027, with judgment expected in the following months.
  • Until the legal process concludes, lenders do not need to calculate or pay compensation under the scheme.
  • If the scheme is upheld and the judgment is not appealed, the FCA expects payments to begin in 2027.

Source: FCA, Car finance claims, updated 13 October 2026.

What lenders still have to do while payments are paused

A partial suspension is not a full stop. The FCA says lenders must comply with the scheme rules that remain in force, which includes sending letters to some customers who are not owed compensation under the scheme. Volkswagen Financial Services describes the steps on its commission complaints page: identifying relevant complaints and agreements, gathering information on them, and analysing them against the scheme rules.

The FCA's consumer page gives the dates. If your agreement began on or after 1 April 2014 and you complained by 30 June 2026, your lender should contact you by 18 November 2026 if nothing is owed. If it began before 1 April 2014 and you complained by 31 August 2026, the date is 18 January 2027. For complaints made after those dates, a lender that finds nothing is owed should tell you within five months.

Two points follow. A letter saying no compensation is due can arrive even while payments are on hold. And, as the FCA stresses, not hearing from your lender does not mean you are owed money.

Should you wait or complain now?

The FCA's consumer page names complaining to your lender as the best thing to do if you have concerns about your car finance, and says you can do it for free. That is not the only reasonable choice, so here are the considerations on each side.

Reasons people choose to complain now

  • The FCA has told lenders to plan for the possibility that the scheme, or parts of it, are quashed. In that case there would be no pause, and lenders would need to handle complaints through their usual process within the usual statutory timescales.
  • The response dates the FCA has published depend on when a complaint was made, so the date of your complaint affects which timetable applies.
  • A complaint puts your agreement in front of the lender, which then has to identify and review it.

Reasons people choose to wait

  • The Tribunal's decision will clarify the rules lenders must apply, and some people prefer to see that first.
  • Payments under the scheme are paused whichever route you take, so a complaint made now will not produce compensation under the scheme before the legal process ends.

Neither choice can guarantee an outcome. If you are unsure, the free guidance service MoneyHelper is a good independent place to start.

How to complain to your lender, step by step

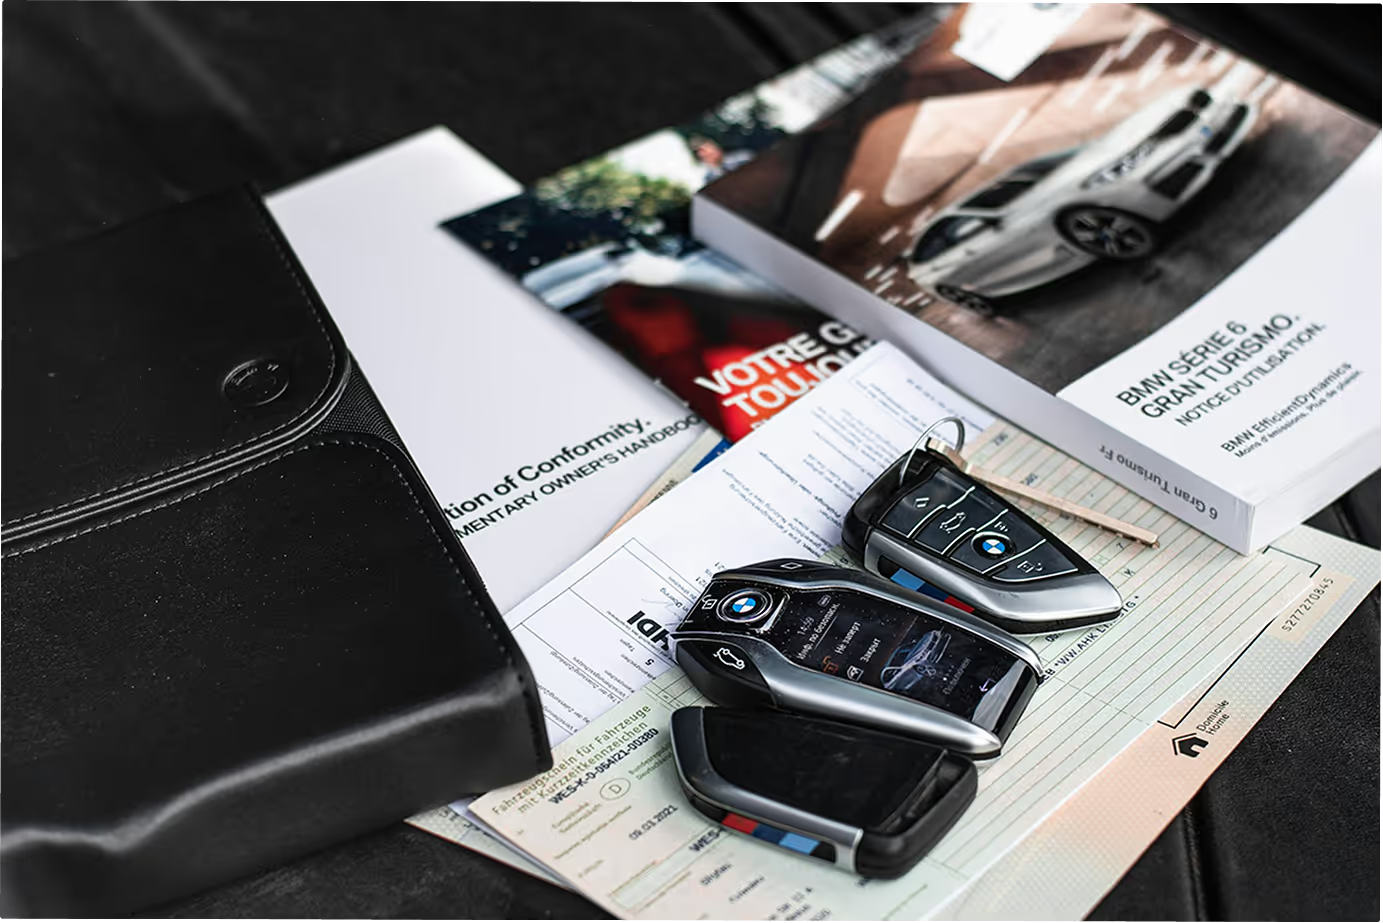
  1. Find your lender. The FCA suggests checking old bank statements, contacting the dealer where you bought the car, and checking your credit file. Our guide to finding your car finance agreement details walks through each route, and our find your agreement page covers the basics.
  2. Contact the lender. The FCA's list of lenders gives contact details, a template complaint letter and links to lenders' own complaint forms.
  3. Wait for the response. The FCA says the timing of a response is uncertain while the scheme is challenged. If a lender sends you a redress decision, you will have one month to accept or challenge it.
  4. Use the Ombudsman if you remain unhappy. The FCA says that if you are unhappy with a redress decision you can complain to the Financial Ombudsman Service, which is free, and that you must do so by the date in your lender's letter.

What to watch for while you wait

  • Use one representative at most. The FCA warns that signing up with more than one claims firm or law firm can mean paying fees to end an agreement, or several success fees, and can delay your payment.
  • Treat unexpected messages with care. The FCA has received reports of scammers posing as car finance lenders and offering fake compensation. Check the lender's details against the FCA's list, never share PINs or passwords, and do not give bank details unless you are certain who you are dealing with.
  • Remember the free route. You do not need a claims management company or law firm to complain or to receive compensation under the scheme, which is free to use. If you choose to use one, check its fees first. Our guide to choosing a car finance claims company covers what to ask.

Our complete guide to car finance claims brings the wider picture together if you want the full background.

Important information

This article is general information, not legal or financial advice. It does not predict the outcome or timing of any complaint, or of the Upper Tribunal's decision. Whether compensation is due depends on the facts of each agreement and on the rules in force.

The information is correct at 21 October 2026 and may change as the legal process develops. This article names lenders only to report publicly available information and does not suggest wrongdoing by any firm.
Frequently Asked Questions

Is the FCA's car finance compensation scheme still going ahead?

The scheme is partially suspended while the Upper Tribunal considers four legal challenges. The FCA says it will defend the scheme and that lenders must keep preparing. The hearing runs from 16 to 26 February 2027, with judgment expected afterwards. Until then, lenders do not need to calculate or pay compensation under it.

Do I have to wait until February 2027 to complain?

No. The FCA says you can complain to your lender now, free of charge. Payments under the scheme stay paused until the legal process ends, so waiting and complaining now both depend on the Tribunal's outcome. The right timing is your decision, and the FCA's guidance is the best place to check the latest position.

Can my lender tell me I am owed nothing while payments are paused?

Yes. The FCA says lenders must keep complying with the scheme rules still in force, which includes writing to some customers who are not owed compensation. The dates depend on when you complained. Equally, not hearing back does not mean you are owed money, as the FCA points out.

Do I need a claims company or solicitor to complain?

No. The FCA says you do not need a claims management company or law firm to complain or to receive compensation under its scheme, and the scheme is free to use. If you choose a representative, check the fees first and avoid signing up with more than one firm.

What happens if the Tribunal rules against the scheme?

The FCA has told lenders to plan for that possibility. If the scheme or parts of it are quashed, there may be no scheme and no pause on complaints, and lenders would need to handle complaints through their usual process within the usual statutory timescales. The outcome remains uncertain until the Tribunal rules.

Key takeaways

The February 2027 hearing sets the next milestone, but it does not change your right to complain or your freedom to choose how.

  • The Upper Tribunal will hear the challenges from 16 to 26 February 2027, and the FCA expects payments in 2027 at the earliest if the scheme is upheld and not appealed.
  • Lenders are still carrying out the parts of the scheme that remain in force, so a no-compensation letter can arrive while payments are paused.
  • You can complain for free without a claims company, and the FCA recommends complaining to your lender if you have concerns.

If you would like help working out whether your agreement may be eligible, you are welcome to check with us. Checking is a first step only and does not mean compensation is due.

Next step

Find out whether your agreement may be eligible.

Check your eligibility with PCP Missold

Sources and references

  1. Financial Conduct Authority, Car finance claims. Last updated 13 October 2026. https://www.fca.org.uk/consumers/car-finance-complaints
  2. Financial Conduct Authority, Motor finance legal challenge to be heard in February 2027. Statement, 13 October 2026. https://www.fca.org.uk/news/statements/motor-finance-legal-challenge-be-heard-february-2027
  3. Financial Conduct Authority, Information for firms on motor finance complaints. https://www.fca.org.uk/firms/information-firms-motor-finance-complaints
  4. Volkswagen Financial Services (UK) Limited, Motor Finance Commission Complaints. Updated 21 September 2026. https://customer.vwfs.co.uk/commission-complaints.html
  5. Insurance Business, Motor finance scheme challenge set for February 2027 hearing. https://www.insurancebusinessmag.com/uk/news/auto-motor/motor-finance-scheme-challenge-set-for-february-2027-hearing-593404.aspx
  6. MoneyHelper, Money guidance. https://www.moneyhelper.org.uk/en/contact-us/money-guidance
Written by
Shane Lowe
Software Developer with 6+ years at Rix Motors, specialising in automotive systems and vehicle finance processes. Shane has extensive knowledge of the car industry and PCP agreements, contributing expert insight on mis-sold PCP claims, dealership practices, and consumer vehicle finance guidance for PCP-missold.co.uk.

NEED TO TALK TO US?

Get in touch or register your interest to keep up-to-date with the latest news and developments in mis-sold agreements.